Free 30-min consultation · No pitch, no pressure 📞 CALL: (949) 536-9733

Self-Directed IRA Disqualified Person Rules: Who Counts and Who Doesn’t
Who is a self-directed IRA disqualified person? The family members, advisors and businesses that count, the relatives who don't, and the deals that can cost an IRA its tax status.
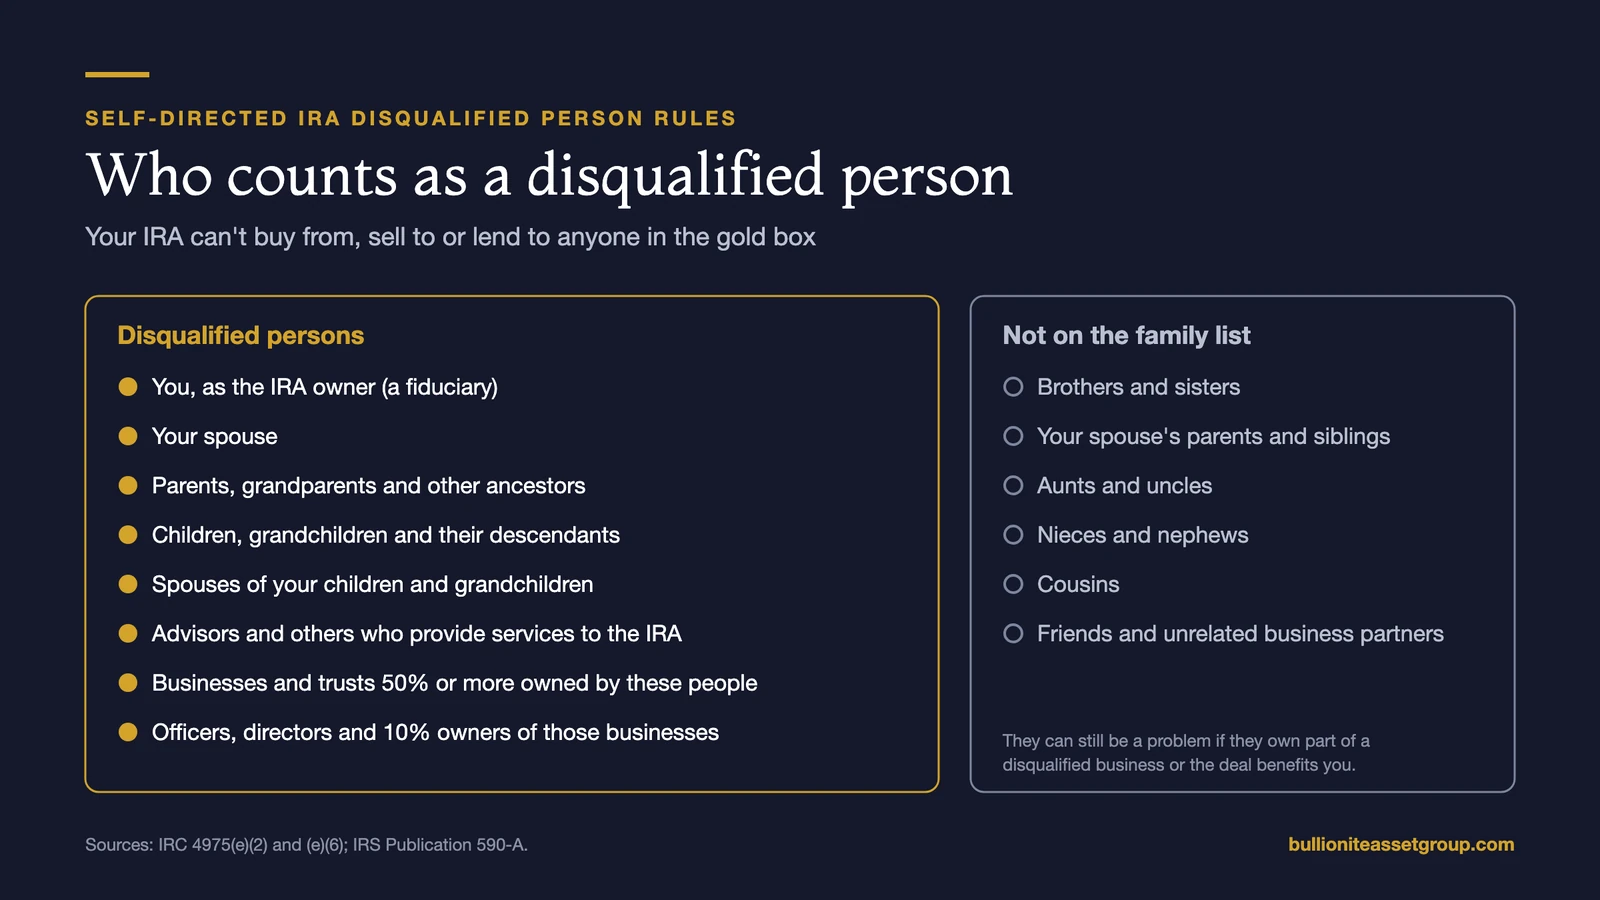
A self-directed IRA disqualified person is anyone your IRA can't do business with: you, your spouse, your parents and grandparents, your children and grandchildren and their spouses, your advisors, and businesses these people control. Deal with one, even at a fair price, and the IRS can treat your whole IRA as distributed.
The family part trips people up. Your brother isn't on the list, but your daughter's husband is. This guide goes through the full list from the tax code, then the business and real estate cases where people most often slip.
What is a self-directed IRA disqualified person?
The IRA disqualified person definition comes from 26 U.S.C. 4975(e)(2), the prohibited transaction section of the tax code. It lists the people and entities a retirement account can't deal with, because a deal with them could let the account's money benefit someone other than the account.
IRS Publication 590-A puts it in one line: "Disqualified persons include your fiduciary and members of your family (spouse, ancestor, lineal descendant, and any spouse of a lineal descendant)." You're your own IRA's fiduciary, because Pub 590-A counts anyone who "exercises any discretionary authority or discretionary control" over the IRA or its assets. In a self-directed IRA, that's you.
So under the self-directed IRA rules, disqualified persons start with you and spread out through your family, your advisors and your businesses. The IRS disqualified person IRA rules are the same for traditional, Roth, SEP and SIMPLE IRAs.
Who counts as a disqualified person?
Here's the full list of disqualified persons for self-directed IRA owners, with the part of the statute each comes from:
| Person or entity | Disqualified? | Why |
|---|---|---|
| You, the IRA owner | Yes | You're the IRA's fiduciary |
| Your spouse | Yes | Family under section 4975(e)(6) |
| Parents, grandparents and earlier generations | Yes | Ancestors |
| Children, grandchildren and later generations | Yes | Lineal descendants |
| Your children's and grandchildren's spouses | Yes | Spouses of lineal descendants |
| Brothers and sisters | No | Not on the family list |
| Your spouse's parents and siblings | No | Not on the family list |
| Aunts, uncles, nieces, nephews and cousins | No | Not on the family list |
| Advisors and anyone providing services to the IRA | Yes | Fiduciaries and service providers |
| Businesses, trusts or estates 50% or more owned by the people above | Yes | Section 4975(e)(2)(G) |
| Officers, directors, 10% shareholders and highly paid employees of those businesses | Yes | Section 4975(e)(2)(H) |
| 10% partners or joint venturers of those businesses | Yes | Section 4975(e)(2)(I) |
Your custodian counts too, as a service provider. That doesn't stop you paying its fees: IRC 4975(d) exempts services needed to run the plan when no more than reasonable compensation is paid.
Is a sibling a self-directed IRA disqualified person?
Sibling relationships don't make anyone a disqualified person. Section 4975(e)(6) limits family to your spouse, ancestors, lineal descendants and their spouses, so brothers, sisters, nieces, nephews and cousins fall outside it. The same goes for your spouse's parents and siblings.
So your IRA can buy a rental from your sister or lend to your nephew's business, as long as the terms are at fair market value. A relative who isn't on the list can still become a problem in a few ways:
- They own a stake in a disqualified business. A 10% partner in an LLC you control is a disqualified person under section 4975(e)(2)(I).
- They run a disqualified business as an officer or director.
- They provide services to your IRA, such as managing its property or advising on its investments.
- The deal benefits you. If your IRA lends to your brother so he can repay money he owes you, the benefit to you makes it prohibited.
Get an independent appraisal for any family deal, even with a relative who isn't on the list. It's your best evidence that the price was fair if the IRS ever asks.
Which businesses are disqualified persons?
A business is a disqualified person when disqualified persons together own 50% or more of it, counting ownership held directly or through other entities. That covers corporations, partnerships, LLCs, trusts and estates.
| Example | 50% test | Disqualified? |
|---|---|---|
| An LLC you own 40% of and your wife owns 15% of | 55% | Yes |
| A construction company your son owns 51% of | 51% | Yes |
| A company you own 30% of and your father owns 25% of | 55% | Yes |
| A company your brother owns 100% of | 0% | No, unless he's disqualified another way |
| A fund where you and your family own 10% | 10% | No, but check whether you run it |
Officers, directors and 10% owners of a disqualified business are disqualified persons too. So if your IRA can't deal with your company, it also can't deal with that company's CEO in a side deal.
Owning a business through your IRA, rather than dealing with one, raises its own questions, which our guide to self-directed IRA business ownership covers. The same goes for an IRA-owned checkbook LLC: you can manage it, but you can't pay yourself from it.
What deals with a disqualified person are prohibited?
Section 4975(c)(1) bans six kinds of dealings between your IRA and a disqualified person, whatever the price:
- Selling, exchanging or leasing property between them.
- Lending money or extending credit, in either direction, including guaranteeing the IRA's loan.
- Providing goods, services or facilities, such as your company managing the IRA's property.
- Letting a disqualified person use the IRA's income or assets, or benefit from them.
- A fiduciary dealing with IRA assets for their own interest.
- A fiduciary receiving payment from a party dealing with the IRA.
The IRS's retirement plan investments FAQs describe these rules as applying to transactions "between an IRA and its owner or beneficiary or between an IRA and a disqualified person." Our guide to self-directed IRA rules and prohibited transactions covers the related traps, and our guide to IRA loans to family covers lending.
Where do disqualified person problems show up in real estate?
Real estate deals cause a lot of them, because family so often sits on the other side. In self-directed IRA real estate, disqualified person mistakes usually come from treating the IRA's property like family property:
- Buying your parents' rental, or selling the IRA's property to your daughter.
- Renting the IRA's house to your son, even at full market rent.
- Hiring your own company, or your son's 51%-owned company, to renovate or manage it.
- Doing repairs yourself, which counts as providing services.
- Guaranteeing the IRA's mortgage, the move that disqualified two IRAs in Peek v. Commissioner.
- Spending a weekend at the IRA's vacation property.
The fix is to keep every role in the deal with people outside the list: the seller, the buyer, the tenant, the lender, the contractor and the manager. Our guides to buying land with an IRA and the non-recourse loan IRA apply the same checks to land deals and IRA borrowing.
What happens if your IRA deals with a disqualified person?
For you as the IRA owner, the IRA stops being an IRA. Under IRC 408(e)(2), a prohibited transaction ends the account's IRA status as of January 1 of that year, and the whole account is treated as distributed to you.
On a $400,000 traditional IRA, that's $400,000 of taxable income in a single year, plus a $40,000 additional tax if you're under 59½. It doesn't matter that only a $20,000 deal broke the rule.
Other disqualified persons who take part owe an excise tax under section 4975: 15% of the amount involved for each year, rising to 100% if the deal isn't corrected. Correcting means undoing the deal as far as possible. That fix isn't open to you as the IRA owner, because your account has already lost its IRA status.
The courts enforce this strictly. In Peek v. Commissioner, two investors used their IRAs to buy a company and then personally guaranteed a loan the company took on. The Tax Court held the guarantees were prohibited even though they ran through the company, as the Journal of Accountancy's case summary explains, and both IRAs were disqualified.
How to check a deal before you sign
- List everyone on the other side of the deal: seller or buyer, tenant, lender, contractor, property manager and any business involved.
- Check each person against the family list.
- For each business, add up what disqualified persons own, directly and indirectly, against the 50% line, and check who its officers and 10% partners are.
- Ask whether anyone on the list benefits, even indirectly, through a fee, a job, a repayment or personal use.
- Get an independent valuation whenever family or a related business is anywhere near the deal.
If any answer is unclear, stop and get it reviewed before the custodian signs.
Have the deal checked before your IRA signs
Most disqualified person problems are visible before closing, when they're still easy to fix. Bullionite helps investors set up a self-directed IRA, map everyone involved in a deal, and structure real estate IRA purchases so no self-directed IRA disqualified person is on the other side. Book a consultation and bring the names involved.
This guide is general information, not tax, legal or investment advice. The rules cited are current for 2026, so check your own situation with a CPA or tax attorney before you act.
FAQ
Is my brother-in-law a disqualified person?
No. Neither your spouse's brother nor your sister's husband is on the family list in section 4975(e)(6), so your IRA can deal with either one at fair market value. A brother-in-law becomes disqualified only through another role, such as a 10% partner or officer of a disqualified business.
Can my IRA hire my son’s company?
No. Your son is a disqualified person, and a company he owns 50% or more of is too, so hiring it to repair, build or manage IRA property is a prohibited furnishing of services. Use an unrelated contractor and pay it from the IRA.
Is my financial advisor a disqualified person?
Usually, yes. IRS Publication 590-A counts anyone who gives investment advice to your IRA for a fee as a fiduciary, and service providers are disqualified persons too. Paying an advisor reasonable fees is allowed, but your IRA can't buy from, sell to or lend to them.
Can my IRA invest in a company my friend owns?
Yes, as long as disqualified persons together own less than 50% of the company and the deal doesn't benefit you personally, for example through a salary or a job there. Friends aren't on the family list, so the usual concern is your own role, not theirs. If your IRA will take a controlling stake, have the structure reviewed first, because a company your IRA controls raises its own prohibited transaction questions.
As the Founder and Chief Investment Officer of Bullionite and Bullionite Asset Group, I’ve built my career on a simple premise understanding the intersection of macroeconomics, commodities, and digital assets to stay ahead of the curve, not under it. My focus is on navigating the complexities of the world’s largest markets spanning the US, the Middle East, and Asia to identify high-value opportunities for alternative investment.
With a specialized focus on Self-Directed IRAs (SDIRAs), I help investors move beyond traditional 401ks by integrating assets like precious metals and cryptocurrency into their retirement strategies. Based in Newport Beach, California, I am dedicated to bridging the gap between traditional finance and the evolving landscape of new age digital assets, ensuring that every strategic move is backed by deep market insight and a commitment to long-term growth.